

Before you tour a single home, get your goals, your budget, and your financing straight. The buyers who slow down here move faster, and with far more confidence, later.
Updated October 2026 · Reviewed by The Johnson Team
Your First Step to Buying a Home in Colorado Springs
The first move in buying a home in Colorado Springs is a focused conversation about what you want this purchase to do for you, held before the market puts a clock on you.
Skip it and you end up looking at the wrong homes, writing offers that miss, and signing paperwork you don’t fully understand because the deadline is already running. Get it right, and every decision after this one gets easier.
This post covers both halves of that groundwork: setting a budget that reflects what Colorado Springs actually costs, and choosing a loan and assistance program that fits. When you’re ready for the next step, Step 2 covers how to search the right neighborhoods.
Part One: Setting Your Home Buying Budget in Colorado Springs
What Should You Look For in a Home? Start With SPACE
Five questions narrow a Colorado Springs home search faster than any filter: size, parking, area, character, and extras.
- Size. How many bedrooms and bathrooms do you need? Think beyond today, a growing family, a home office, guests who visit often. Build in room to breathe.
- Parking. Garage, driveway, street parking. How many vehicles, and how much do you want to deal with snow and ice each winter?
- Area. Where do you want to live? Close to work, schools, family. Commute times matter more once you’re living them daily.
- Character. Clean and modern, or older with charm and history? And just as important, what’s the neighborhood vibe: quiet cul-de-sac or walkable and social?
- Extras. Storage matters more than people expect. Closets, a garage workbench, an attic, a shed. Think through what you own and where it’ll live.
Answer these five and your search narrows fast, fewer wasted showings, more homes that actually fit.
We don’t run this as a canned questionnaire. It’s a conversation, and it’s often where two goals turn out to pull against each other. Proximity to work versus school district is a common one. When that happens, we usually talk about choosing into a specific school rather than assuming you have to move to be zoned for it.
How Much House Can You Actually Afford in Colorado Springs?
Less than your pre-approval says. Two local costs, property tax that varies by district and insurance priced for the hail corridor, are the ones a listing’s estimated payment usually understates.
The smart first move is finding your ceiling. Get pre-approved so you know what a lender will back, then treat that number as a maximum, not a target. It’s the most a bank will lend you, not the amount you should spend, and the number you qualify for and the number you’re comfortable paying every month are rarely the same. Ask your lender to run the full payment at your approval ceiling and again at ten percent below it. Seeing both monthly numbers side by side is usually what settles which one you actually want to shop at.
- Property tax. Colorado keeps property tax low by design, but it isn’t uniform. A home in one Colorado Springs zip code can be taxed noticeably lower than a similar home a few minutes away, driven by school district lines and the metro districts attached to many newer subdivisions. A metro district fee can add hundreds a year, and it doesn’t expire. We pull the home’s actual tax record and check for a metro district before you commit, not after.
- Insurance. Colorado Springs sits in the hail corridor, and premiums here run well above the national average. A roof’s age and hail history can affect not just your premium but whether a carrier will write the policy at all. Get a quote early, while there’s still room to fold it into your budget or walk away.
Which Colorado Springs Neighborhood Fits Your Budget?
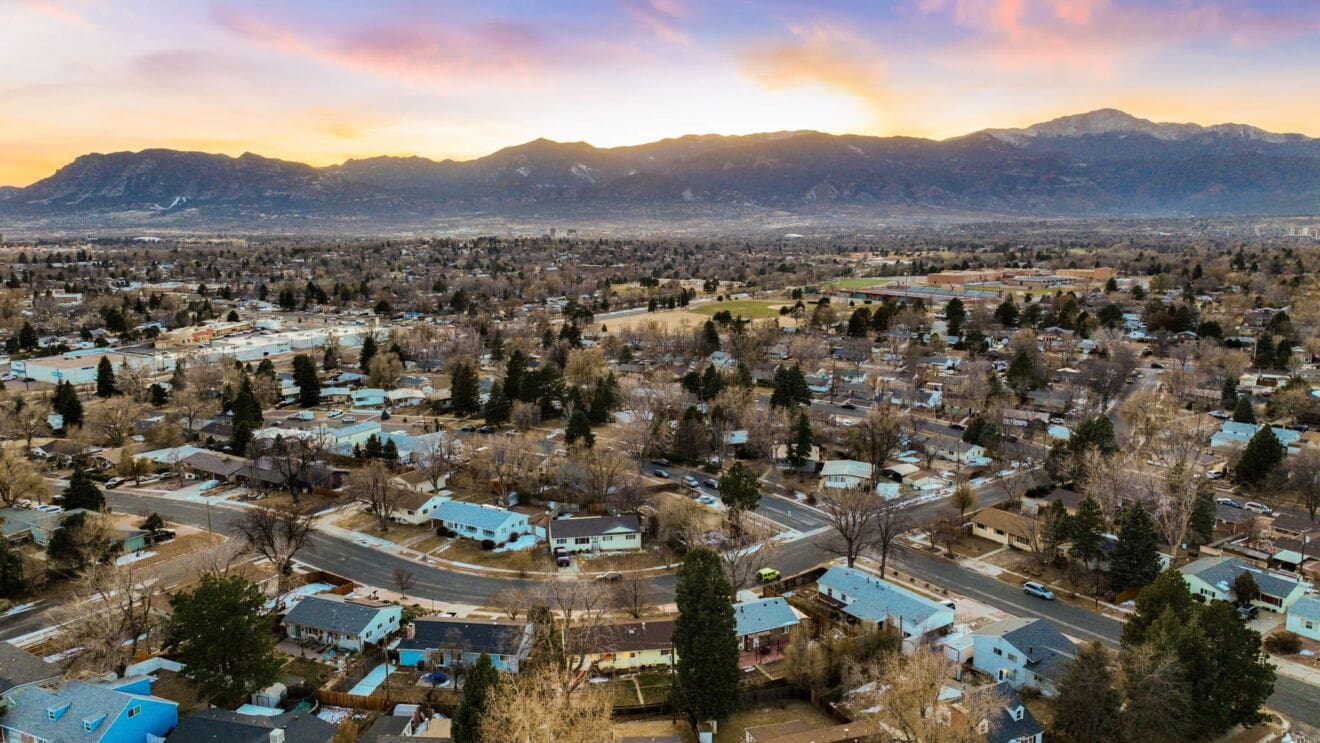
HOA dues, tax district, and insurance risk change block by block here, not just neighborhood by neighborhood, and all three land on your monthly payment.
Commute and schools are the obvious things to weigh. The ones that catch buyers off guard are the costs tied to the exact address.
- HOAs are common in the newer master-planned communities on the north and east sides, meaning dues plus covenants that can govern paint colors, fencing, and RV or boat parking. Older central and west-side neighborhoods often have none.
- Schools matter down to the district. D20 in the north, D49 out east, D38 in Monument, D12 around Cheyenne Mountain, each with its own reputation and pull on demand. Boundaries split neighborhoods, so confirm the exact assignment for a specific address rather than trusting the neighborhood’s reputation.
- Insurance risk climbs in the foothills and along the wildland edge, where some pockets see real difficulty finding a carrier at all. Beautiful settings, but price the insurance before you fall for the view.
If you’re still narrowing the map, our neighborhood guides break down the areas one at a time.
Should You Buy New Construction in Colorado Springs?
New construction here comes with real incentives and one long-term cost most buyers miss: a metro district mill levy that outlasts every rate buy-down that sold you on the home.
Single-family, townhome, condo, and patio home don’t just look different. They carry different maintenance, HOA structures, lending rules, and resale behavior, so decide early which one fits how you want to live.
New construction is its own decision, and Colorado Springs has a lot of it. The advertised base price is a starting point, not the final number. Lot premiums and finish upgrades add up quickly, and the model home you tour is usually fully optioned. Builders often offer incentives like rate buy-downs or closing-cost credits, worth real money, but usually tied to the builder’s preferred lender, so it’s worth running the numbers both ways.
Watch for metro districts. Many builders use metro districts to finance the roads, sewers, and other infrastructure a new neighborhood needs. That debt gets passed to homeowners through the district, and the mill levy that funds it can run well above a typical county tax rate. Before you buy new construction, ask directly whether the neighborhood sits in a metro district and what the current mill levy is, and get it in writing.
How Often Does the Home You Want Actually Come Up?
Sometimes only a handful sell in an entire year. An MLS look-back report tells you whether your wish list is realistic before you spend six months proving it isn’t.
Buyers tend to assume the right house is always out there, one search away. For a specific combination of neighborhood, size, and price, that isn’t always true.
Your agent can run a look-back report on the MLS showing exactly how many homes matching your criteria have sold in the last three to six months. If the answer is forty, you can be patient. If the answer is four, something in your criteria needs to flex, and it’s far better to learn that now than after a season of watching nothing come up.
What Paperwork Do You Sign Before You Start Touring?
Two documents come early in Colorado. One is a disclosure that explains how agents work, the other is a real contract, and that contract doesn’t have to lock you in for a year.
The first is a disclosure called the Definitions of Working Relationships. It isn’t a contract, it explains how an agent can work with you in Colorado.
The second is the buyer agency agreement, the Exclusive Right-to-Buy. That one is a real contract, and it spells out how long it lasts, the area it covers, and how your agent is paid.
You don’t have to commit to a year. You can start with a shorter term, often 30 to 90 days. We build an easy-out provision into every agreement we sign. If we aren’t the right fit for you, you’re free to walk, no hard feelings, no hoops. We’ve been doing this in Colorado Springs since 2010, across more than 3,600 families, and we’ve never needed to trap anyone into staying.
The agreement also spells out how your agent is paid, which raises the question most buyers have: who actually pays for it? In Colorado, you’re responsible for your agent’s compensation, but in most cases the seller agrees to cover it for you. We advocate hard for exactly that result, because we never want our pay to be a factor in you getting the right house at the right price.
Bottom line: The buyers who slow down here are the ones who move fastest and most confidently later.
Part Two: Loan Options and Down Payment Assistance in Colorado
The biggest myth is that you need 20 percent down. Most buyers here put down far less, and many qualify for assistance they never knew existed.
Do You Need a Pre-Approval, or Is Pre-Qualification Enough?
A pre-qualification is an estimate based on what you tell a lender. A pre-approval is verified with documents and a hard credit pull. Not every buyer needs the deeper one before they start looking.
A pre-qualification is quick, usually with a soft credit pull or none at all. A pre-approval goes further, the lender verifies your income, assets, and credit with documentation, and it’s what sellers take most seriously.
Here’s where we differ from the generic advice you’ll read elsewhere. We don’t think every buyer needs a full pre-approval before they start looking. Whether you need the deeper version depends on your situation, how competitive the price point is, and how confident you already are in your numbers. When it’s the right call, we can connect you with lenders who complete a pre-qualification in as little as fifteen minutes with no credit impact at all.
What Down Payment Assistance Is Available in Colorado Springs?
You don’t need 20 percent down. Colorado and El Paso County both run assistance programs, and two matter most here: CHFA and El Paso County Turnkey Plus.
Conventional loans can start near 3 percent down, FHA at 3.5 percent, and VA and USDA at zero for those who qualify. For most first-time buyers, the bigger question is what assistance is available on top of that.
- CHFA. The state housing authority offers first-time buyer loans with down payment assistance, tied to income limits, a credit score usually around 620, and a homebuyer education course.
- El Paso County Turnkey Plus. Pairs a 30-year fixed mortgage with down payment assistance worth 2 to 5 percent of your loan, structured as a 0 percent second mortgage that’s forgiven over time.
Every program shares the same fine print: income caps, credit minimums, and education requirements worth confirming early. A good loan officer walks you through which one fits, usually in a quick phone call, and we’ll point you to one.
Which Loan Type Should You Use in Colorado Springs?
The loan you choose changes which homes you can realistically win, because each one carries a different appraisal standard and a different reputation with sellers.
Here’s how the four main options compare.
Conventional
- Mortgage insurance
- PMI below 20% down, drops off at enough equity
- Credit profile
- Strongest terms with higher scores
- Appraisal standard
- Value only
FHA
- Mortgage insurance
- Usually stays for the life of the loan
- Credit profile
- Built for lower scores
- Appraisal standard
- Value plus property condition
VA
- Mortgage insurance
- None
- Credit profile
- Flexible for eligible service members
- Appraisal standard
- Value plus Minimum Property Requirements
USDA
- Mortgage insurance
- Annual fee, lower than FHA
- Credit profile
- Moderate, with income caps
- Appraisal standard
- Value plus property condition
- Conventional is often the best terms if you have strong credit and a larger down payment. Private mortgage insurance applies below 20 percent down, but unlike FHA, it falls off once you reach enough equity.
- FHA is built for buyers with lower credit or a smaller down payment. The tradeoff is mortgage insurance that, on most FHA loans today, stays for the life of the loan unless you refinance. The FHA appraisal also checks property condition, so peeling paint, a bad roof, or safety issues can trigger required repairs before closing.
What Should VA Buyers Know Before They Use the Benefit?
For eligible service members and veterans, the VA loan is one of the strongest available: no down payment, no monthly mortgage insurance, competitive rates. Five things are worth knowing before you assume it’s simple.
- The funding fee. Zero down doesn’t mean free. Most buyers pay a VA funding fee rolled into the loan, roughly 2.15 to 3.3 percent of the amount. On a $300,000 purchase, your actual loan balance the day you close can be closer to $310,000. You may qualify for an exemption through VA disability or Purple Heart status.
- Zero down still needs cash. You’ll still cover earnest money, inspection costs, and sometimes the appraisal fee up front. When you work with us and follow your agent’s guidance on service providers, we guarantee up to $5,000 in those up-front costs if the deal falls through for reasons within our control. Terms apply, ask your agent for the details.
- The appraisal is stricter. A VA appraisal checks Minimum Property Requirements on top of value, and those issues usually have to be fixed before the loan can close.
- The VA isn’t your lender. It guarantees the loan, banks and mortgage companies lend it, so rates and fees vary by lender. Shop more than one.
- You can use it more than once. You can reuse the benefit after selling, restore your entitlement, and in some cases carry two VA loans at once.
Does Colorado Springs Qualify for a USDA Loan?
Colorado Springs proper does not. USDA loans are built to encourage homeownership in rural and outer-suburban areas, and the city itself sits outside the eligible map.
A surprising amount of the surrounding area does qualify, including parts of Falcon, Peyton, Fountain, and Security-Widefield. Eligibility is drawn by address, not by town, so two homes a few streets apart can land on opposite sides of the line. Check the specific property on the USDA eligibility map before you rule the program in or out.
How Do You Compare Mortgage Lenders Without Losing Money?
Get every quote on the same day, and compare the APR and the fees behind it rather than the headline rate.
Mortgage rates move daily, which makes the most common shopping mistake easy to fall into: comparing one lender’s quote from today against another’s from last week. That isn’t a comparison, it’s a coin flip.
We’re not paid to recommend any lender, and we have no financial stake in who you choose. What we have is the benefit of working with hundreds of lenders since 2010, across more than 3,600 families, so when one consistently stands out on communication and follow-through, the whole team hears about it. That’s the kind of thing our 2,700+ five-star reviews are built on.
Bottom line: Know your numbers before you shop, take the assistance you qualify for, compare lenders the right way, and choose a loan that fits both your finances and the homes you’re targeting.
Once your budget and financing are settled, the next stage is the search itself: which Colorado Springs neighborhoods fit, how to hear about the right homes first, and what to look for once you’re standing in one. That’s covered in Step 2, Search With a Plan.
Next: Step 2: Search With a Plan · Back to the Buying Overview
Good To Know
Common Questions About Strategy and Financing
Less than most people think. Conventional loans can start near 3 percent down, FHA around 3.5 percent, and VA or USDA loans can go to zero down for buyers who qualify. Your exact number depends on the loan program and your lender, and we’ll get you a clear answer early so it’s not a surprise later.
Colorado and El Paso County both offer programs for qualifying first-time and moderate-income buyers, including CHFA and El Paso County Turnkey Plus, and some come as grants or forgivable second mortgages rather than debt you repay. Eligibility and available funding change, so we’ll point you to current programs and a trusted lender who can confirm what you qualify for.
Not always. It depends on your situation, how competitive the price point is, and how confident you already are in your numbers. A pre-qualification is often enough to start touring, and we’ll tell you when it’s time to go deeper.
In Colorado, yes, a written agreement is required before an agent represents you. It doesn’t have to run a year. Terms of 30 to 90 days are common, and we build an easy-out provision into every agreement we sign, so you’re never locked in with a team that isn’t working for you.
Want To Learn More?
Let’s get started with a one-on-one conversation about your goals.